
Her expression tightens with recognition. She’s seen this play out before. Regina takes out her phone. Bank policy prohibits recording, Diane says sharply. I’m not recording. Regina types quickly—a message to someone. Just checking consumer protection guidelines. Who did she text? What did she say? That answer is on its way.

Diane Whitmore refreshes her screen. There’s a problem with your credit authorization form, Miss Carter. You didn’t initial box 3B. Regina leans in. I initialed every box. That’s my signature right there. Diane shakes her head, already pushing a new form across the desk, marked in red for missing information.
The system shows it’s incomplete. You’ll need to fill out another. Federal regulations, I’m afraid. Regina compares the two forms—they’re identical. What exactly is missing? Box 3B. Like I said, Diane’s tone sharpens. I understand this might be confusing, but these are compliance requirements. Confusing? The word lingers like an insult.
Jamal whispers, “Mom, can we just do it?” Regina gives a slight shake of her head. She knows what’s happening. She’s encountered this before in other settings—the extra scrutiny, the manufactured hurdles, the assumption she won’t grasp the rules. She completes the second form anyway, initialing every box with deliberate clarity, then slides it back.
Diane inspects it as if it’s counterfeit—holding it to the light, checking the signature three times. Beyond the glass walls, another scene plays out. A white couple in their 30s approaches another banker. The woman’s hair is in a messy bun; the man wears a faded college sweatshirt.
They’re opening a joint account. The banker smiles, jokes with them. No one asks for their utility bill twice. No one questions their address. No one demands extra paperwork. Seven minutes later, they’re finished, leaving hand in hand, laughing. Back in Diane’s office, 23 minutes have passed. Diane sets the form down.
Now about the $500. I’m going to need verification—a letter from the Rosewood Community Center on official letterhead confirming Jamal’s hourly wage and total earnings for a checking account. Regina’s voice stays even, but there’s steel beneath it. That’s not standard procedure. It is when I deem it necessary.
Diane folds her hands. And for the birthday money, I’ll need a sworn statement from the relatives who gave it—names, addresses, amounts, and their relationship to Jamal. Jamal stares at her. You want my grandparents to write a statement about birthday money? Bank Secrecy Act requirements. We have to verify the source of all funds.
Diane’s smile is thin and sharp. Surely you understand. We can’t just accept cash without knowing where it came from. Regina’s jaw tightens. The Bank Secrecy Act applies to transactions over $10,000. My son is depositing $500. For a moment, Diane’s composure slips—she didn’t expect Regina to know that. I have discretionary authority, she says quickly. And I’m using it.
If you can’t provide the documentation, I can’t open the account. Can’t or won’t? Diane stands, asserting control physically after losing ground. Miss Carter, I don’t appreciate your tone. I’m trying to protect this institution from fraud. Fraud? Regina repeats slowly. You think my 16-year-old son is committing fraud with his community center paycheck. I think there are patterns we’re trained to recognize. Diane crosses her arms. Red flags. And frankly, this situation has several.
What patterns? Regina rises to match her. What red flags? Be specific. Through the glass walls, everyone can see now. Kevin at reception has stopped greeting customers. Ms. Patterson at the teller window has paused her transaction. A man near the ATM openly stares. Diane’s face flushes—aware of the audience, growing more aggressive.
High-value deposits from minors, vague employment claims, reluctance to provide standard documentation. She ticks them off on her fingers. And your attitude, Miss Carter, isn’t helping your son’s case. My attitude? Regina raises her voice just enough to carry. I’ve provided every item on your account-opening checklist. You’ve asked for extras that aren’t policy, and now you’re calling my compliance attitude. I’m calling your hostility attitude.
There’s a difference between a customer and someone looking to cause problems. Jamal’s voice cracks. We’re not trying to cause problems. I just want to deposit my paycheck. Diane barely glances at him. Then perhaps your mother should let me do my job instead of questioning every procedure. Regina pulls out her phone again.
I said no recording. Diane’s voice rises. I’m not recording. I’m documenting. Regina types quickly—another message sent to someone important. Diane snaps. That’s it. I’m not comfortable continuing this application. I think you should leave. Leave. Regina remains seated. You’re refusing service.
I’m exercising my right to decline an account when I have concerns about the legitimacy of the customer relationship. Legitimacy of the customer relationship. Regina repeats it slowly, letting each word land. What concerns do you have about our legitimacy? Diane opens her office door—a clear dismissal.
I don’t need to explain every operational decision to you. This conversation is over. No, it isn’t. Regina stays seated, because you’re going to tell me, in front of all these witnesses, exactly what concerns you have about my family. The lobby falls silent. Eight customers are watching now. Three tellers. Kevin.
A security guard near the entrance starts toward them. Diane’s hands tremble—anger or fear, hard to tell. Fine. You want specifics? Your son shows up with $500 in cash. You live in a neighborhood you clearly can’t afford. You claim to work in healthcare, but you’re dressed like—she stops herself.
Like what? Regina’s voice is dangerously soft. Like someone who doesn’t belong in a private bank. The words spill out. This isn’t a community bank. We serve established clients with verified income and assets—people who contribute to the economy, not—
Not what? Diane has gone too far to stop. The audience, the pressure, the loss of control—it all collides. Not people like you. Her voice echoes across the marble. People who come in with demands and attitudes and expect us to ignore protocol because you’ll cry discrimination if we don’t. I’ve managed this branch for six years, and I know who belongs here.
She steps closer, looming over Regina and Jamal. You want the truth? Fine. I have concerns about your funds, your financial situation, and whether you even understand how banking works. And yes, I’m refusing service because this is my branch, and I decide who opens accounts. Her voice drops, cold and final.
People like you always play the victim. You expect special treatment, and when we follow policy, you make it about race. Well, it’s not. It’s about standards—professional standards. This bank has a reputation to maintain. And frankly, Miss Carter—she looks Regina up and down with open contempt—
You’re nobody. You don’t belong here. This isn’t some welfare office where you can walk in off the street. We serve successful people, real professionals. Maybe try a community credit union somewhere more appropriate.
The silence that follows is absolute. Someone gasps. Ms. Patterson covers her mouth. Kevin looks like he might be sick. The security guard, Marcus Thompson—a 52-year-old Black man, retired police officer—stops in place. He knows exactly what he just heard.
Jamal’s eyes fill with tears. He blinks hard, but one slips free. His mother has just been called nobody in public. He’s been treated like a criminal, and he can’t stop it. Regina’s expression doesn’t change, but something behind her eyes does. She’s no longer angry—she’s resolved.
Her phone, still in hand, shows a message sent three minutes ago. Timestamp 11:02 a.m. The recipient isn’t visible from Diane’s angle, but the message is simple:
Discrimination incident. Downtown branch. Diane Whitmore. Stand by.
Regina studies Diane for a long moment, then speaks, her voice carrying through the silent lobby. You’re absolutely sure about that? That I’m nobody? That I don’t belong here?
Diane, emboldened, lifts her chin. Completely sure.
Good. Regina’s voice is ice. I wanted to be certain before I made the call. She raises her phone to her ear—and Diane Whitmore’s world begins to unravel. The number dials. It rings once, twice. Diane crosses her arms, confident. Who are you calling? Your lawyer? Good luck with that. The call connects.
Regina switches to speaker. Her tone is professional, cold, controlled. Janet, this is Regina.
A woman’s voice responds immediately, crisp and alert. Dr. Carter, I got your text. What happened?
Dr. Carter. Diane’s smile falters.
Regina speaks clearly, loudly enough for the entire lobby to hear. I’m at our downtown Portland branch with my son. We came to open a student checking account. The branch manager, Diane Whitmore, refused service. She questioned the legitimacy of my son’s $500 deposit from his summer job, demanded non-standard documentation not required by policy, and accused us of fraud.
Diane’s face drains of color.
When I asked for clarification, she told me that people like me don’t belong in this bank, that we should go somewhere more appropriate, and that I’m nobody. Regina pauses. She said this in front of approximately 15 witnesses, including employees and customers. Several are recording.
The voice on the line—Janet Woo, Chief Human Resources Officer of First Western Financial Holdings—responds instantly. Is Miss Whitmore present?
She is. She’s listening.
Diane Whitmore. Janet’s tone drops sharply. Do not move. Do not speak to anyone. Do not leave that building.
Diane grips her desk for balance.
Dr. Carter, Janet continues, shifting to controlled urgency, I sincerely apologize. This is a catastrophic failure of everything we stand for. I’m issuing a suspension notice now. Regional Director Brooks is on his way—he’ll arrive in six minutes.
Thank you, Janet. Regina ends the call.
The lobby is completely silent. Every eye is on Diane. Her mouth opens, then closes. Dr. Carter, you’re—who are you?
Before Regina can respond, Diane’s computer chimes—a new email. Her hands shake as she opens it.
From: Janet Woo, Chief Human Resources Officer, First Western Financial Holdings
To: Diane Whitmore
CC: Robert Brooks, Regional Director; Legal Department
Subject: Immediate Suspension – CEO Directive
Miss Whitmore, you are hereby suspended without pay, effective immediately, by direct order of CEO Dr. Regina Carter. Cease all work activities. Surrender your access badge, office keys, and all company property. Security has been notified and will escort you from the premises within 15 minutes. A formal investigation will begin Monday morning. You are prohibited from contacting any employees, customers, or representatives of First Western Financial Holdings regarding this incident.
Failure to comply will lead to immediate termination and possible legal action. Janet Woo, Chief Human Resources Officer, First Western Financial Holdings. Diane reads it once, then again. The color drains completely from her face. CEO. Her voice is barely audible. You’re the CEO. Regina rises. She isn’t tall, but in this moment, she seems to fill the entire room.
I’m Regina Carter, founder and chief executive officer of First Western Financial Holdings—the company that owns Cascade National Bank and 49 other branches across six states. Her voice is quiet, but it cuts like a blade. I built this company from a single branch 12 years ago. I sit on the board of three Fortune 500 companies.
I oversee $8 billion in assets. She steps closer. And you just told me I’m nobody. Diane collapses into her chair. Her hands shake so badly she can barely hold the armrests. I didn’t. I didn’t know. You didn’t say. If I had known who you were. If you had known, you would have treated us differently. Regina’s voice is steel.
That’s exactly the problem. Respect shouldn’t depend on knowing someone’s title. Marcus, the security guard, appears in the doorway. He’s been standing nearby, hearing everything. He looks at Diane without sympathy. Ms. Whitmore, I need your badge, keys, and company phone. Diane is crying now, mascara streaking. Please, I have kids.
I have a mortgage. I need this job. I didn’t mean you meant every word. Regina doesn’t raise her voice—she doesn’t need to. You said people like me don’t belong here. You called my son a fraud. You told me to find somewhere more appropriate in front of your employees, in front of customers, in front of my son. She glances at Jamal, now standing, watching his mother step fully into her power for the first time in his life.
You meant it, Regina continues. And now you’ll face the consequences. Miss Patterson, the teller who’s been observing everything, steps forward. Dr. Carter, I’m Evelyn Patterson. I’ve worked here for 11 years. I need to tell you this isn’t the first time I’ve seen her do this to other customers. I reported it twice. Nothing happened.
Regina pulls out her phone, opens her notes app. M. Patterson, would you be willing to provide a formal statement—dates, names, specific incidents? Absolutely. Kevin from reception joins them. I documented everything and emailed HR 30 minutes ago. Timestamps, witness names, everything. Another teller, a young Latino man named Carlos, speaks up.
I saw her do this to a black couple last month. Same questions about their money, same attitude. The evidence is stacking up. This isn’t a single incident—it’s a pattern. Diane is bent over her desk, sobbing. Marcus stands waiting, professional but firm. Ms. Whitmore, he says quietly. It’s time to go.
She fumbles with her badge, drops it, picks it up with shaking hands—her office keys, her company phone—everything that marked her as branch manager. Six years gone in six minutes. As Marcus escorts her toward the door, she makes one last attempt. Dr. Carter, please. I’m sorry. I didn’t understand. Regina doesn’t turn. You understood perfectly.
You just didn’t think there would be consequences. The glass door shuts behind Diane Whitmore. She’ll never work in banking again. Diane is halfway across the lobby when Robert Brooks bursts through the main entrance. He’s 46, usually composed, but now he looks like he’s been running. His tie is loose.
His face is flushed. He scans the room, spots Regina, and heads straight for her, ignoring everyone else. Dr. Carter. He’s breathing hard. I got your message. I was at my daughter’s soccer game. I drove here as fast as I could. He glances at Diane, frozen near the door with Marcus. Is it true? Everything you texted—every word.
Robert turns to Diane, his voice trembling with barely controlled anger. You told Dr. Regina Carter—our CEO, our founder, the woman who built this entire company—that she’s nobody. The remaining customers pull out their phones. This will be everywhere by tonight. Diane can barely speak. I didn’t know.
She didn’t tell me. How was I supposed to? You weren’t supposed to know. Robert’s professionalism cracks. You were supposed to treat every customer with respect. That’s literally your job. Marcus clears his throat. Still beside Diane, he turns slightly toward the crowd. His voice carries the authority of 30 years in law enforcement.
For those who don’t know, he says, addressing customers and staff, Dr. Regina Carter founded First Western Financial Holdings 12 years ago. She started with one branch in Seattle and expanded it to 50 branches across six states. She’s CEO of the parent company that owns this bank, and she sits on the boards of Intel, Providence Health Systems, and Kaiser Permanente.
He pauses, letting it settle. She’s been featured in Forbes, Fortune, and the Wall Street Journal. She was Oregon Business Magazine’s executive of the year two years in a row. Before finance, she was a neurosurgeon at OSU. She has more power in one phone call than anyone in this building will have in their entire career.
The lobby is silent except for the soft classical music overhead—the absurd normalcy of it. Marcus looks at Diane. And you told her she’s nobody. Diane’s legs give out. She drops hard onto the marble floor, back against the wall. She’s still crying, but now it’s the kind that comes with total collapse.
Her career, her reputation—everything is gone. Regina walks over to Jamal, who’s watching with wide eyes. She places a hand on his shoulder. You asked me why I didn’t tell her who I was from the start, she says quietly, though others can hear. This is why. Because the janitor deserves the same respect as the CEO.
The teacher deserves the same respect as the board member. If service depends on knowing someone’s title, then it’s not service—it’s a performance. She looks at Robert Brooks. How long has Diane Whitmore been branch manager here? Six years. And in those six years, how many discrimination complaints were filed against her? Robert’s jaw tightens.
He pulls out his phone, checks the records. According to HR, seven formal complaints—all dismissed as personality conflicts or misunderstandings. Seven, Regina’s voice turns cold. Pull up the demographic data on those complaints. Robert types. His face pales. All seven were from customers of color—five Black, two Latino.
Ms. Patterson steps forward. Dr. Carter, I filed two of those complaints. I’m one of three Black employees at this branch. I told HR Diane treated customers differently depending on who walked in. They said I was being oversensitive. Kevin joins her. I sent an email three months ago documenting five incidents where Diane requested extra verification from Black and Latino customers she never asked of white customers. I never got a response.
Carlos, the young teller, adds, Last month she made a Black woman cry. The woman had a PhD—a professor at Portland State. Diane questioned her employment three times and asked for tax returns just to open a basic savings account. The woman filed a complaint. Nothing happened.
Regina turns to Robert. Nothing happened. Seven complaints, clear patterns—and nothing happened. Robert looks like he wants to disappear. Dr. Carter, I—we have policies, training—I don’t know how—
I know exactly how. Regina cuts through him. I review training completion records every quarter. Diane completed her annual anti-discrimination training in 14 minutes last year. The course is designed to take 90 minutes. She clicked through every module as fast as possible.
She pulls something up on her phone and shows him. The case study in module 3 describes exactly what she did today—requesting non-standard documentation, questioning fund legitimacy without cause, using policy as a shield for discrimination. She passed the quiz with 100%. But she didn’t read it. She didn’t learn it. And no one followed up.
The system failed at every level. Regina walks to Diane, still seated on the floor, and crouches to meet her eyes. You asked if I knew who you were. Diane’s voice is hoarse. You’re right. I would have treated you differently. I would have—
You would have treated me like that couple. Regina gestures toward where the young white couple opened their account earlier. Eight minutes. No questions. No extra documentation. Smiles and pleasantries. That’s what everyone deserves—not just CEOs, not just white people. Everyone.
She stands. I dressed casually today. I drove a regular car. I didn’t show credentials because I wanted to see how my employees treat ordinary customers—and now I know. Robert’s phone buzzes. He checks it, then looks at her. Legal wants to know how you’d like to proceed. They recommend immediate termination, a formal investigation, and outreach to affected customers.
Agreed. Regina doesn’t hesitate. But I want more. I want a full audit of every branch. I want customer service metrics broken down by demographics. I want to know how widespread this is. Yes, ma’am.
Regina turns to Jamal. You still need a checking account. Kevin practically runs to his desk. I’ll open it right now—premium account, all fees waived for two years. And on behalf of everyone here who isn’t—he glances at Diane—like that, I’m so sorry.
Regina nods. Thank you, Kevin. I saw you documenting everything. That took courage. While Kevin processes the account, Regina looks at the text she sent earlier—11:02 a.m., to Robert Brooks: Discrimination incident. Downtown branch. Diane Whitmore. Standby. She sent it the moment Diane demanded verification for the birthday money.
That was 23 minutes ago. She gave Diane 23 minutes to change course—multiple chances to stop, to reconsider, to treat them with basic dignity. Diane refused every one. And now, sitting on the marble floor of the bank she once managed, Diane Whitmore finally understands what she’s lost.
Not just a job, not just a career—her entire identity. For six years, she was the branch manager. She had power. She decided who belonged. And in six minutes, she learned she’d used that power against the one person who could take it all away—the woman she called nobody. The woman who is, in fact, everything.
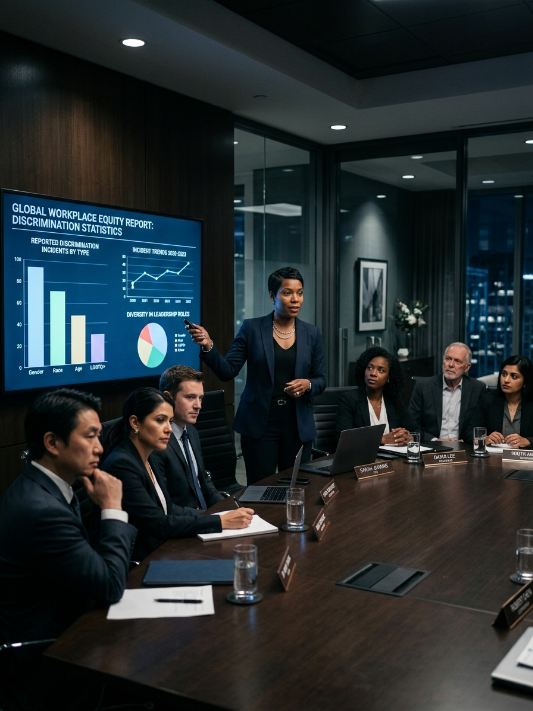
Two weeks later, Regina Carter sits at the head of a conference table at First Western Financial Holdings headquarters in Seattle. Ten board members, the chief legal officer, Janet Woo from HR. Robert Brooks looks more nervous than usual. On the screen behind Regina, a single number glows in white against a dark background: 31.
Thirty-one customers, Regina begins evenly, received discriminatory treatment from Diane Whitmore over the past 18 months—not six years, just the last year and a half. That’s how far back we could confirm using transaction logs, security footage, and employee testimony. She clicks to the next slide—a demographic breakdown.
Of those 31 customers, 23 were Black, six were Latino, two were Middle Eastern—zero were white. She lets the silence sit. This wasn’t implicit bias. This was a pattern.
The chief legal officer, Martin Webb, interrupts. Dr. Carter, before we proceed, I need to state for the record that these findings are preliminary. And Martin, Regina’s voice is ice, we have video evidence, statistical analysis, 17 employee testimonies, and 12 dismissed customer complaints. This isn’t preliminary.
This is documented fact. She clicks again. Split-screen footage appears. On the left, Diane Whitmore greets a white couple in their 40s—smiling, laughing—processing their account in eight minutes flat. No questions about employment. No requests for additional documentation.
On the right, Diane sits with a Black woman in her 30s—no smile, arms folded—spending 23 minutes questioning her and making three separate requests for extra paperwork. The woman leaves without opening an account. Same day, Regina says, same account type, same initial deposit, just two hours apart. She cues up another comparison. A white man in his 20s wearing a hoodie and ripped jeans.
He opens a checking account in six minutes. Diane jokes with him about his university sweatshirt. A Black teenager in a button-down and khakis is questioned for 18 minutes about his funds, asked if his parents know he’s at the bank. Diane even calls his employer to verify his paycheck before continuing. The pattern, Regina continues, is consistent, documented, and indefensible.
Robert Brooks clears his throat. We’ve contacted all 31 customers. Twenty-seven accepted our apology and restitution offer. Four are considering legal action independently. What’s the average settlement? a board member asks. $2,500 per customer plus fee waivers for five years. Total exposure: $77,500. Janet Woo brings up the spreadsheet.
That’s only direct restitution—it doesn’t include legal fees if any of the four proceed with lawsuits. Regina advances to the next slide, showing training completion records. Diane Whitmore completed mandatory anti-discrimination training four times in six years, with an average completion time of 16 minutes. The course is designed to take at least 90 minutes.
She clicked through every module, answered quiz questions using the on-screen review sheet, and collected her certificate. Regina clicks again. Seventy-three percent of our branch managers complete training the same way. They’re checking a box—not learning, not changing. The room shifts uncomfortably. We have a systemic problem, Regina states flatly. Diane Whitmore is a symptom.
The disease is that we built a compliance system that lets people pretend they’re complying. Martin Webb tries again. With all due respect, Dr. Carter, one branch manager’s behavior doesn’t necessarily indicate—Regina cuts him off with a single click. A map of all 50 First Western Financial Holdings branches appears.
Five are highlighted in red. Five branches, five different managers, all showing statistically significant disparities in how they treat customers of different races. She zooms into the data. Branch 12 in Tacoma—Black customers wait an average of 14 minutes longer than white customers for the same services.
Branch 27 in Sacramento—Latino customers are three times more likely to have account applications delayed for additional review. Branch 8 in Boise—Middle Eastern customers are flagged for fraud screening at five times the rate of white customers with identical transaction patterns. The board is silent now.
We found this in two weeks of analysis, Regina continues. Two weeks using data we already had. This has been happening for years, and no one looked. Janet Woo stands and takes over. Dr. Carter asked us to examine not just individual complaints, but patterns across the organization. We analyzed 200,000 customer interactions from the past three years. The results are troubling.
She clicks through charts showing response times, approval rates, documentation requests, fraud flags, and service quality scores—all broken down by race. In every metric, Janet says, customers of color receive measurably worse service than white customers. Sometimes it’s seconds, sometimes minutes, sometimes the difference between approval and denial—but it’s consistent across branches, states, and the entire operation.
A board member, Patricia, speaks up. Are you saying our entire company is discriminatory? I’m saying, Regina replies, that we built systems without proper oversight. We promoted managers without adequate screening. We implemented training that doesn’t train. And when employees raised concerns, we dismissed them as personality conflicts.
She pulls up emails and internal HR communications, all marked confidential. Evelyn Patterson reported Diane Whitmore in March last year. HR response: customer service styles vary—no action needed. Kevin Morrison reported her in November. HR response: manager discretion is within policy—case closed. Carlos Mendoza reported her in February this year. HR never responded at all.
Regina looks directly at Janet Woo. Why? Janet’s expression tightens. Our HR team was understaffed. We prioritized legal liability over employee concerns. We had a culture that protected managers over customers and frontline staff. And that ends today, Regina says. She advances to a new slide: Proposed reforms. The list is extensive.
Immediate actions: terminate Diane Whitmore for cause—already completed. Place four other managers on administrative leave pending investigation. Retain a third-party firm to audit all branches for discriminatory patterns. Establish a $500,000 fund for customer restitution and community outreach.
Policy changes: mandatory bias testing before promotion to management. A mystery shopper program with diverse participants. Quarterly visits to every branch. Real-time AI monitoring of transaction patterns to flag disparities. An anonymous employee hotline with guaranteed investigation within 72 hours. Customer complaints escalate to executive level after a single HR dismissal.
Training overhaul: replace click-through modules with in-person workshops requiring demonstrated competency. Monthly case study reviews led by diversity consultants. Quarterly one-on-one assessments with random branch staff. Failure to pass results in immediate suspension and retraining.
Accountability measures: branch manager bonuses tied to equitable service metrics, not just profitability. A public annual diversity report showing service quality by demographics. A board-level equity and inclusion committee with authority to override executive decisions. Employee whistleblower protections with financial incentives for reporting discrimination.
Patricia and Gwyn study the list. This is aggressive. The cost alone—The cost of doing nothing, Regina interrupts, is our reputation, our customer base, and potentially our banking license. The FDIC takes discrimination seriously. So does the Consumer Financial Protection Bureau. If they investigate and find what we found, we won’t control the narrative.
Martin Webb looks uneasy. Dr. Carter, some of this could expose us to additional liability. If we acknowledge systemic issues—Then we acknowledge them. Regina’s voice is final. I didn’t build this company to value legal protection over doing what’s right. We failed 31 customers—likely more. We’re going to fix it.
She clicks to the final slide: a photo of Jamal Carter sitting in the bank lobby two weeks earlier, trying not to cry while his mother is called nobody. This is my son, Regina says quietly. He’s 16. He got his first job. He came to open his first bank account and learned that someone in authority could look at him and decide he’s suspicious, criminal, unwelcome—based on nothing but how he looks.
She lets the image linger. He learned that lesson at my bank, in my company, because I didn’t do enough to prevent it. She looks around the table. That stops now. The vote is unanimous. All reforms approved.
After the meeting, Robert Brooks approaches Regina. Dr. Carter, I want to apologize. Diane reported to me. I should have seen the pattern. You should have, Regina agrees. So should HR. So should I. We all failed. She pauses. But now we fix it. How long until the third-party audit is complete?
Six weeks for a preliminary report, three months for a full review. I want weekly updates. And Robert? She meets his gaze. You’re a good regional director, but you missed this. Everyone in your position will receive additional training on identifying discrimination—including you. Yes, ma’am.
Later that evening, Regina sits in her home office reviewing employee testimonies. Seventeen people came forward once they felt safe—seventeen who saw something wrong and tried to report it. One stands out, from Marcus Thompson, the security guard.
I’m a Black man who worked as a police officer for 30 years. I know what discrimination looks like. I saw Diane do it dozens of times. I documented what I could. I reported it twice to branch management. Nothing happened. When Dr. Carter walked in that day, I recognized what was happening immediately.
Part of me was relieved that someone with real power was finally experiencing what regular customers go through. Maybe now something would change. I hate that it took the CEO being discriminated against for anyone to care, but I’m grateful something is finally happening.
Regina reads it three times. He’s right. It shouldn’t have taken the CEO experiencing discrimination for the system to respond—but it did. And that’s the most damning evidence of all. The system wasn’t broken because it lacked policies, but because those policies were only enforced when someone powerful enough demanded accountability. Everyone else could be ignored. Not anymore.
Regina opens her laptop and begins drafting an email to all 50 branch managers. Subject line: “Change is coming. Be ready.” In two weeks, the mystery shopper program launches—real customers, diverse backgrounds, unannounced visits—to test whether reforms are real or just performance.
This time there will be consequences. This time people are watching. This time it’s not just about Diane Whitmore. It’s about whether an entire institution can choose to be better than it was.
Three months after that Saturday morning, the transformation is visible. The downtown Portland branch has a new manager—Sandra Kim, 39, Korean-American, formerly assistant manager at the Beaverton location. She greets every customer the same way: warm, professional, no assumptions.
On a Tuesday afternoon, a young Black man in a hoodie walks in, nervous—his first time opening an account. Sandra completes everything in nine minutes, asks about his job with genuine interest, welcomes him to the bank. He leaves smiling. This is how it should have been all along.
Ms. Patterson is still there. So is Kevin, now in management training. Carlos has been promoted to senior teller. The people who reported discrimination and were ignored are now helping rebuild trust.
But what about Diane Whitmore? She no longer works in banking—can’t. Her termination was recorded as fired for cause: discrimination. It’s a matter of public record.
Every background check reflects it. Her banking license was revoked after an ethics review. The state banking commission determined her actions violated professional conduct standards. She tried to challenge it—hired a lawyer. The lawyer dropped her case after reviewing the evidence: 17 witness statements, security footage, and statistical analysis showing a pattern across 31 customers.
There was nothing to defend. She applied for jobs outside banking—a retail management role. They Googled her name, found the news coverage. Bank manager fired after calling CEO nobody. The story went viral—6 million views. She didn’t get the job. Her husband filed for divorce four weeks after the incident. He told his lawyer he couldn’t stay married to someone like that.
Their children took his last name. She left Portland. Some say she’s in Idaho now, working at a call center, barely covering rent. Others say she left the state entirely. No one knows for sure. No one cares—because Diane Whitmore no longer matters. The system that enabled her does. First Western Financial Holdings released its first annual equity in banking report in September.
The data is public, transparent, uncomfortable. The report shows that before reforms, Black customers waited an average of 4.2 minutes longer than white customers for service. Now it’s 0.3 minutes. Latino customers were denied accounts at 2.7 times the rate of white customers with identical financial profiles. Now it’s 1.1 times.
Still not equal—but closer. The mystery shopper program runs continuously. Diverse participants visit branches unannounced, testing for discriminatory treatment. Two managers were fired in the first month—not for dramatic incidents like Diane’s, but for patterns—for asking different questions, for subtle bias that would have gone unnoticed before.
The anonymous hotline receives about 40 calls per month. Every one is investigated within 72 hours. Five employees have received financial rewards for reporting discrimination. The message is clear: speaking up is rewarded, not punished. Branch manager bonuses are now tied to equity metrics. If your branch shows disparities across racial groups, you don’t get paid.
Simple as that. Suddenly, every manager cares deeply about equal treatment. The training is real now—live workshops, role-playing scenarios. A Black facilitator asks white managers what they would do if a young Black man walked in with cash. They must answer out loud, confront their assumptions, prove their understanding. The program isn’t perfect.
Some branches still show disparities. Some managers still carry bias. But now there’s accountability, measurement, consequences. All 31 customers who experienced discrimination received restitution. Most accepted the bank’s apology. Three pursued additional legal action and received confidential settlements.
One customer—a Black woman who was made to feel like a criminal for depositing her PhD stipend—used her settlement to start a nonprofit helping people of color navigate financial discrimination. Regina Carter now chairs the newly formed equity and inclusion committee. She reviews data quarterly, visits branches unannounced, sits in on training sessions, and reads every hotline complaint personally.
She doesn’t trust the system to fix itself—so she watches it constantly, because she knows what happens when no one is watching. She experienced it firsthand in her own bank, with her own son. At the downtown Portland branch, a new plaque now hangs near the entrance. It wasn’t there three months ago.
It reads, “We serve everyone with equal dignity and respect. If you experience discrimination, report it. We will listen.” Below it, a QR code links directly to the anonymous hotline. Sandra Kim insisted on putting it there. She says it’s a promise—to customers, to employees, to everyone who walks through those doors.
Some promises are kept. Some aren’t. This one is tested every single day. So far, it’s holding. Six months later, Regina and Jamal sit at their kitchen table. His debit card—the premium account from that day—rests between them, worn now, used regularly, ordinary.
Do you think things actually changed? Jamal asks. Or did people just get better at hiding it? Regina doesn’t give him comfort. Both. Some changed because they had to. Some because they wanted to. Some just perform compliance better now. That’s why we measure, watch, and hold people accountable. It’s exhausting.
It is. But the alternative is worse. The alternative is what happened to us happening to someone without a CEO’s phone number—someone who just walks away. Jamal traces the edge of his card. I still think about what she said—that we’re nobody. I know. Does it get easier?
No. But you get stronger. You learn that someone calling you nobody says everything about them—and nothing about you. She pauses. And you use whatever power you have to make sure they can’t do it again.
That’s the real lesson—not revenge, not dramatic justice—accountability, systems, follow-through. Diane Whitmore’s story isn’t about one bad person being punished. It’s about a system that allowed her to discriminate for six years, dismissed complaints, protected managers over customers, and confused checking boxes with real change.
It’s about what happens when someone with power decides to use it. But here’s the uncomfortable truth: Regina Carter had power. She could make one call and end a career. What about everyone else? The customers who faced the same discrimination but didn’t have the CEO’s number. The employees who reported problems and were ignored—they deserved the same protection, the same accountability, the same justice.
They didn’t get it until someone powerful enough experienced it firsthand. That’s what we can’t forget. Systems don’t change from moral inspiration—they change when staying the same becomes too costly. When the CEO gets discriminated against, when the story goes viral, when reform becomes unavoidable.
So here’s the question: have you ever seen someone abuse power based on assumptions about who belongs—at a bank, a store, a school, anywhere? Did you speak up, document it, report it—or stay silent because it wasn’t happening to you?
The system changed for Regina Carter because she had power. What about everyone else? If you’ve experienced discrimination, document everything—names, dates, exact words, screenshots. Record if legal. File formal complaints. Get written responses.
If you witness discrimination, don’t look away. Be a witness. Provide statements. Your voice might tip the balance. If you hold power like Diane did, ask yourself what assumptions you’re making, who you’re treating differently, what biases shape your decisions.
The difference between Diane and accountability wasn’t that she was uniquely terrible. It was that she finally discriminated against someone who could enforce consequences. That shouldn’t be the requirement for justice. But until it isn’t, we document, report, speak up, and hold systems accountable.
Like this video if you believe accountability matters. Subscribe for stories about systems that change. Share this with someone who needs to see it. Justice isn’t one person getting fired—it’s building systems where the next teenager doesn’t need his CEO mother just to open a checking account.
It’s making dignity the default, not the exception. See you next time.
